Your First Home scheme: Bellway forecasts more building but warns buyers may wait
Your First Home could increase Bellway’s annual building by around 10%, its chief executive says, while uncertainty over the launch risks delaying first-time buyers’ purchases.
What happened
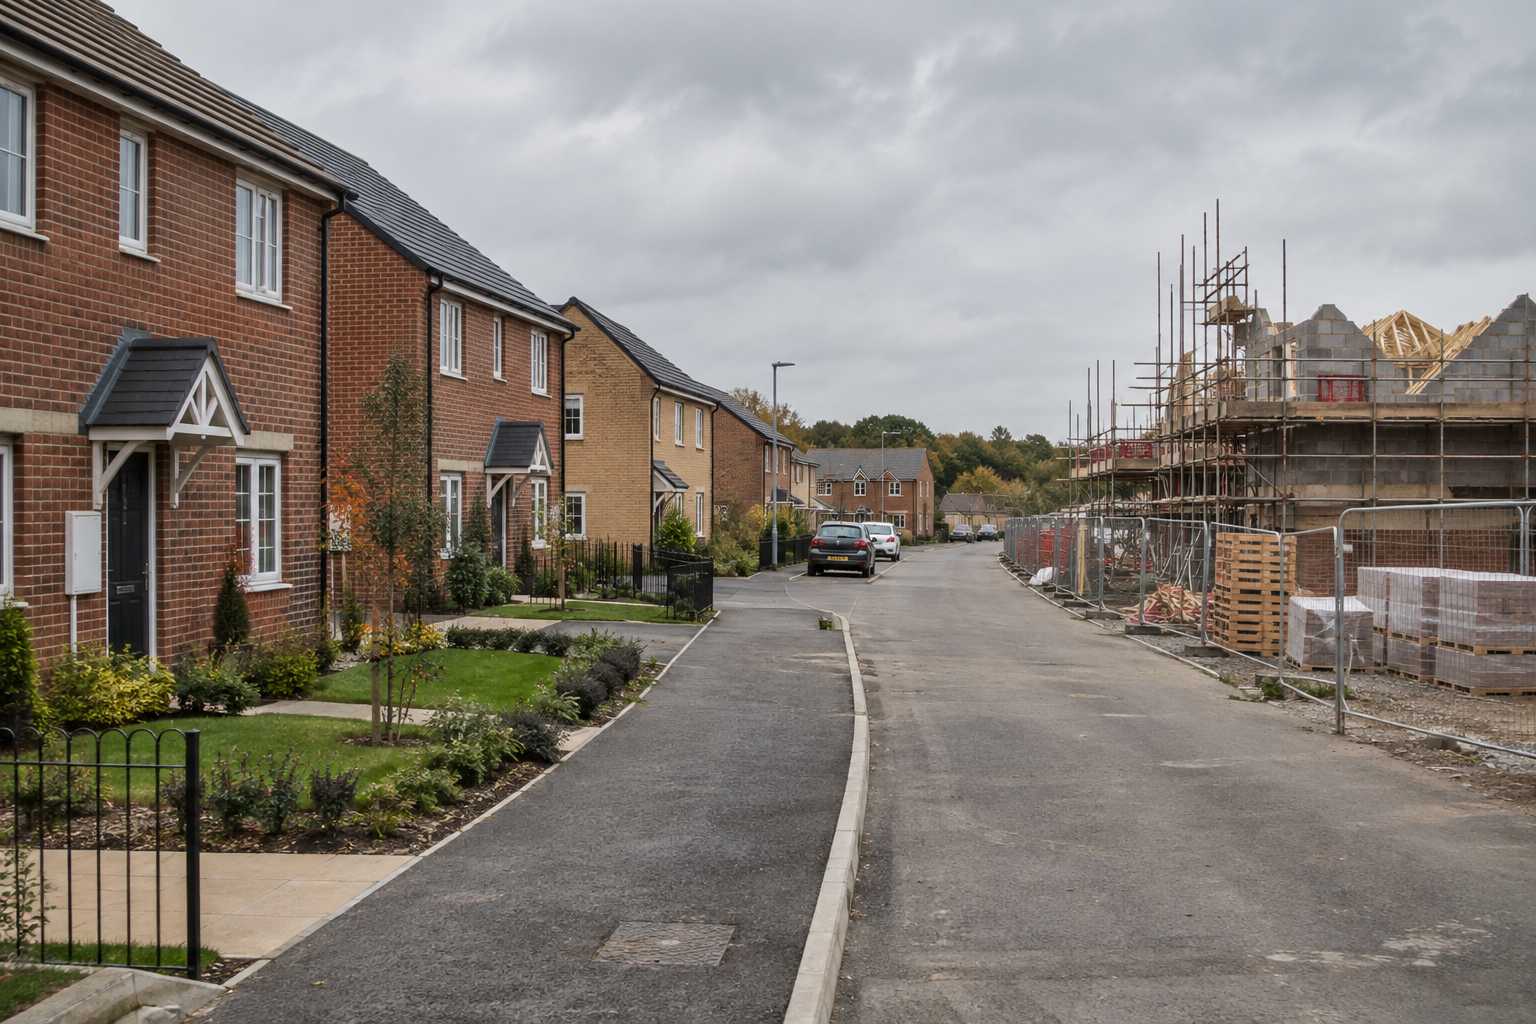
Your First Home could help more first-time buyers purchase a newly built property, but Bellway has warned that uncertainty over its start date could temporarily discourage purchases. Chief executive Jason Honeyman said the programme could eventually increase the builder’s annual completions by around 10%, according to the Guardian’s report on 13 October 2026.
The announced programme applies to England and would provide eligible buyers with a government-backed equity loan worth 20% of the purchase price. Buyers would need a minimum deposit of 2.5%. It is intended for first-time buyers purchasing a new-build house or flat, rather than an existing home.
Household income limits and property price ceilings are planned, the report said. Those restrictions would determine which buyers and properties qualify, making the programme more targeted than previous Help to Buy initiatives. The reported announcement did not specify the thresholds, so it does not yet establish whether an individual household would be eligible.
Full details, including when applications or purchases could begin, are expected from John Healey in his first Budget as chancellor on 28 October 2026. That is an expected announcement date, not a confirmed opening date for the programme. Buyers considering postponing a purchase therefore still lack a timetable against which to assess that decision.
Honeyman said the programme, together with a market recovery, could help Bellway return to at least 10,000 annual completions. He put the earliest possible period for that outcome at the 12 months starting in September 2027. His estimate concerns Bellway’s own production and is not a forecast for the increase in housebuilding across England.
The background
Bellway’s immediate outlook is weaker than the longer-term opportunity described by its chief executive. The company expects to complete between 9,000 and 9,400 homes in its current financial year, against 9,695 in the previous year. It attributed the lower target to a smaller order book and continued pressure on customer demand.
The builder reported forward orders covering 4,981 homes, with a combined value of £1.4bn. A year earlier, the equivalent figures were 5,285 homes and £1.5bn. An order book records future business rather than completed sales, so these figures describe the pipeline Bellway has available as it works towards its annual delivery target.
Bellway also reported construction cost increases of between 3% and 4%, while expecting its average selling price to remain broadly unchanged at about £325,000 over the coming year. That average is a company-wide forecast, not a proposed Your First Home price limit. The figures provide company-level context for the wider debate about housebuilding output and developer costs.
For the year ending 31 August 2026, Bellway reported revenue of £3.16bn, up 13% on the previous year. Underlying profit before tax rose 5.7% to £305.7m. The Guardian reported that revenue exceeded analysts’ expectations; the stronger completed-year results sit alongside the company’s more cautious forecast for the year ahead.
For buyers, an equity loan is different from a grant: it is borrowing linked to a share of the property’s value. A smaller required cash deposit does not, by itself, establish whether a purchase is affordable over time. That distinction is relevant to the separate question of how first-time buyer mortgage payments compare with rent, rather than just how quickly a deposit can be saved.
Read moreFirst-time buyer mortgage payments exceed rent for 56%
What people are saying
Honeyman welcomed the programme’s potential to help first-time buyers, drawing on Bellway’s experience of earlier Help to Buy schemes. He said that experience informed his estimate of an approximately 10% increase in volumes. It remains a company assessment of a programme whose full operating rules have not yet been announced.
The chief executive also identified a possible short-term drawback: prospective purchasers may hold off until support becomes available. His warning was about the timing of demand, not a reported count of cancelled purchases. The source gave no estimate of how many buyers might wait or how long any slowdown could last.
Bellway’s longer-term financial ambition includes a return on equity of 15%, Honeyman said. He linked the route towards that target and at least 10,000 annual completions to both the new programme and a recovery in the market. His comments therefore did not present government assistance alone as sufficient to deliver those outcomes.
The Guardian reported that Andy Burnham’s announcement roughly a fortnight earlier had prompted housebuilder share prices to rise by more than 10%. Bellway’s shares rose 2% on 13 October, although they remained more than a quarter below their level at the start of the year. Share-price movements reflect investor expectations, rather than confirmed home purchases or additional completions.
The report identified Persimmon, MJ Gleeson, Taylor Wimpey and Bellway as likely beneficiaries of the programme. It expected less benefit for Berkeley Group, given its focus on higher-priced London homes, and Vistry Group, which has moved towards affordable and social housing. Those were reported assessments of the companies’ market positions, not statements of final scheme eligibility.
What happens next
The next scheduled point for further information is the Budget on 28 October. The income ceilings, property price limits and launch arrangements will be important to anyone comparing a purchase now with a possible supported purchase later. Until those details are published, the announced deposit percentage cannot be treated as an offer available to every first-time buyer.
The repayment terms of the equity loan will also matter to household budgets. The supplied report did not set out interest charges, fees or detailed repayment conditions, so buyers should not assume the new programme will reproduce the rules of an earlier scheme. Those missing terms prevent a complete comparison of the support with an ordinary mortgage-funded purchase.
A buyer using an equity loan would still need to arrange funding for the rest of the purchase and meet the relevant lender’s requirements. A low minimum deposit does not remove mortgage affordability checks. Buyers comparing finance can also consult the separate reporting on how quickly mortgage deals are being withdrawn, although individual products will need checking when an application is made.
The decision to wait involves more than eligibility: it also depends on whether a suitable new-build home is available at a workable price. Bellway’s expected average selling price does not establish what a particular development will charge. Buyers considering alternatives can distinguish a developer’s offer from the broader evidence on homes selling below their asking prices.
For Bellway, the practical test will be whether support converts prospective interest into orders and then completed homes. Its 10% estimate should be read alongside the lower current-year production target and the stated need for a market recovery. The September 2027 starting point for a possible return to 10,000 completions makes this a longer-term prospect, rather than an immediate increase in supply.
Why this matters
For first-time buyers in England, the announced 2.5% minimum deposit could reduce the initial savings needed for an eligible new-build purchase. It does not yet show the full cost of ownership or establish who qualifies. Bellway’s forecast points to the possibility of more homes being built, but on a longer timetable and with a market recovery also needed. The Budget details will be more useful to individual buying decisions than the builder’s output estimate alone.
Your questions answered
+What is the Your First Home scheme?
It is an announced programme for eligible first-time buyers purchasing a new-build house or flat in England. It would provide a government-backed equity loan covering 20% of the purchase price.
+How much deposit do I need for Your First Home?
The announced minimum buyer deposit is 2.5% of the purchase price. Buyers would still need funding for the remaining purchase costs and would have to meet the relevant eligibility and mortgage requirements.
+When does Your First Home start?
The reported announcement did not confirm a launch date. Further details are expected in John Healey’s Budget on 28 October 2026; that should not be treated as the scheme’s opening date.
+What is the income limit for Your First Home?
Household income caps are planned, but the supplied report did not state the thresholds. Property price limits are also planned, with further details expected at the Budget.
+Can I use Your First Home to buy an older house?
The announced programme is for new-build houses and flats in England. It does not cover purchases of existing homes under the terms described in the report.
+Is a Your First Home equity loan free money?
No. An equity loan is borrowing linked to a share of a property’s value, rather than a grant. The report did not provide the new programme’s detailed interest, fee or repayment conditions.
+Will Your First Home mean more houses are built?
Bellway’s chief executive estimates it could increase the company’s annual completions by around 10%. His forecast is not a guarantee, and he also linked a return to 10,000 homes a year to a market recovery.
+Should I delay buying until Your First Home launches?
The available details do not establish whether waiting would benefit a particular buyer. The launch date, income caps, price limits and repayment terms remain important unknowns. Bellway has warned that some prospective buyers may postpone purchases.
This story draws on reporting first published by Guardian Property.
Robert Ashdown, Period Property Specialist
Robert writes about caring for older, listed and period homes, including damp, structural movement and conservation rules. He has reported on heritage and housing for over fifteen years.